Tax preparation can often feel stressful for a small business owner, especially when tax season arrives and financial records are incomplete, transactions are uncategorized, or supporting documents are missing.
But one important question is:
Does tax preparation actually start during tax season?
The answer is no.
Tax preparation starts much earlier—with proper recording, categorization, reconciliation, and review of business transactions throughout the year.
If the bookkeeping is accurate and organized, tax preparation becomes much easier because the tax preparer already has the financial information needed to review the business and prepare the tax return.
So, what should a small business have ready before starting tax preparation?
Let’s go step by step.
1. Start With All Business Income
The first question is:
How much income did the business earn during the year?
A business may receive income from different sources, such as:
- Sales
- Services
- Online payments
- Credit card payments
- Bank transfers
- Other business income
All business income should be properly recorded in the accounting records.
The tax preparer needs complete information about the business’s income before determining how it should be reported.
Why is this important?
If some income is missing from the books, the financial statements may not show the complete picture of the business.
Therefore, the first step is:
Identify → Record → Review all business income.
2. Review and Categorize Business Expenses
After income, the next question is:
Where did the business spend its money?
Businesses have many different types of expenses:
- Rent
- Salaries and wages
- Advertising
- Office supplies
- Software
- Professional fees
- Business travel
- Utilities
- Insurance
- Repairs and maintenance
- Other business expenses
But simply recording an expense is not enough.
The transaction needs to be categorized correctly.
For example, if a business spends $5,000 on advertising, it should be properly identified and categorized as an advertising expense rather than simply being placed into a general or miscellaneous category.
Why does categorization matter for tax preparation?
Because the tax preparer needs to understand what the business actually spent the money on.
Correct categorization makes it easier to identify and review expenses that may qualify for deductions under the applicable tax rules.
Wrong categorization can make potentially deductible expenses harder to identify, review, and properly report.
3. Collect Receipts and Supporting Documents
Now ask:
Can we support the transactions recorded in the books?
Supporting documents may include:
- Invoices
- Receipts
- Bills
- Bank statements
- Credit card statements
- Loan documents
- Purchase documents
- Payroll records
- Other relevant business records
Good bookkeeping is not only about recording numbers. It is also about maintaining the information needed to understand and support those numbers.
4. Reconcile Bank and Credit Card Accounts
Another important question is:
Does the accounting record agree with the bank and credit card statements?
Bank reconciliation helps identify:
- Missing transactions
- Duplicate transactions
- Incorrect amounts
- Unrecorded bank charges
- Unusual transactions
- Timing difference
- Missing transactions
- Duplicate transactions
- Incorrect amounts
- Unrecorded bank charges
- Unusual transactions
- Timing differences
For example, the accounting system may show $100,000 of business transactions, while the bank records show transactions that have not yet been recorded.
Before tax preparation, these differences should be reviewed and understood.
5. Review Accounts Receivable
Next, review:
Who still owes money to the business?
Accounts receivable represents amounts customers owe to the business.
The business should review:
- Outstanding customer invoices
- Old receivables
- Customer balances
- Payments received
- Uncollectible or questionable balances
This helps ensure that the accounting records properly reflect the business’s receivables and related transactions.
6. Review Accounts Payable
Now ask the opposite question:
What does the business still owe to its vendors or suppliers?
Accounts payable may include:
- Vendor bills
- Supplier invoices
- Professional fees
- Utilities
- Other unpaid business expenses
Reviewing accounts payable helps make sure expenses and liabilities are properly recorded and that no important transactions have been missed.
7. Review Payroll and Payroll-Related Records
If the business has employees, payroll information becomes an important part of tax preparation.
Review:
- Payroll records
- Employee wages
- Employer payroll-related amounts
- Payroll tax records
- Required payroll forms and filings
- Payroll-related reconciliations
The exact forms and requirements depend on the business, employees, jurisdiction, and applicable tax rules.
8. Review Fixed Assets and Depreciation
Another important question is:
Did the business purchase equipment, computers, vehicles, furniture, or other long-term assets during the year?
For example:
A business purchases a computer for $5,000.
Should it simply be recorded as office expense?
Not necessarily.
The nature of the purchase needs to be reviewed to determine the appropriate accounting and tax treatment.
Therefore, before tax preparation, review:
- Fixed asset purchases
- Asset additions
- Asset disposals
- Existing fixed assets
- Depreciation records
- Supporting purchase documents
The appropriate tax treatment depends on the applicable tax rules.
9. Separate Business and Personal Expenses
This is particularly important for small businesses.
Ask:
Is this expense actually related to the business?
Sometimes business owners use the same bank account or credit card for both business and personal transactions.
For example:
- Business advertising → Business expense
- Office rent → Business expense
- Personal shopping → Personal expense
These transactions should not simply be treated the same way because they were paid from the same account.
Proper identification and categorization help the bookkeeper and tax preparer distinguish business transactions from personal transactions.
10. Review Loans and Liabilities
The business should also review its loans and other liabilities.
Check:
- New loans
- Loan payments
- Principal payments
- Interest payments
- Credit card balances
- Other business liabilities
A loan payment may contain both principal and interest, and these components may have different accounting and tax treatments.
Therefore, the transaction should be reviewed rather than simply recorded as one expense.
11. Review the Financial Statements
After completing the bookkeeping review, prepare and review the financial statements.
The main statements include:
Profit & Loss / Income Statement
Shows:
Income – Expenses = Profit or Loss
Balance Sheet
Shows:
Assets = Liabilities + Equity
Cash Flow Statement
Shows how cash moved through the business.
The financial statements provide a summarized view of the transactions recorded throughout the year.
Before tax preparation, ask:
Do these numbers make sense?
If revenue looks unusually high, an expense category suddenly increases, or an account has an unusual balance, it should be investigated before moving forward.
12. Compare With the Previous Year
Another useful step is to compare the current year’s financial information with the previous year.
For example:
| Category | Previous Year | Current Year |
|---|---|---|
| Revenue | $500,000 | $550,000 |
| Advertising | $20,000 | $60,000 |
| Rent | $30,000 | $32,000 |
| Travel | $15,000 | $45,000 |
If advertising increased from $20,000 to $60,000, we should ask:
Why did advertising increase so much?
Maybe the business expanded its marketing.
Or maybe some transactions were incorrectly categorized.
This type of review can help identify unusual transactions before tax preparation.
13. Review Prior-Year Information
The previous year’s tax return and accounting records can also be useful when preparing the current year’s tax work.
Review information such as:
- Prior-year financial statements
- Prior-year tax return
- Carryforward items, where applicable
- Fixed asset information
- Loans and liabilities
- Other relevant tax information
This can help the tax preparer understand changes from the previous year and identify information that may need to be carried forward or reviewed.
14. Identify Missing Information
Before starting the final tax preparation, ask:
Is anything missing?
For example:
- Missing bank statements
- Missing receipts
- Missing invoices
- Missing loan documents
- Missing payroll information
- Uncategorized transactions
- Unreconciled accounts
- Unknown transactions
It is better to identify these issues before tax preparation rather than discovering them while preparing the tax return.
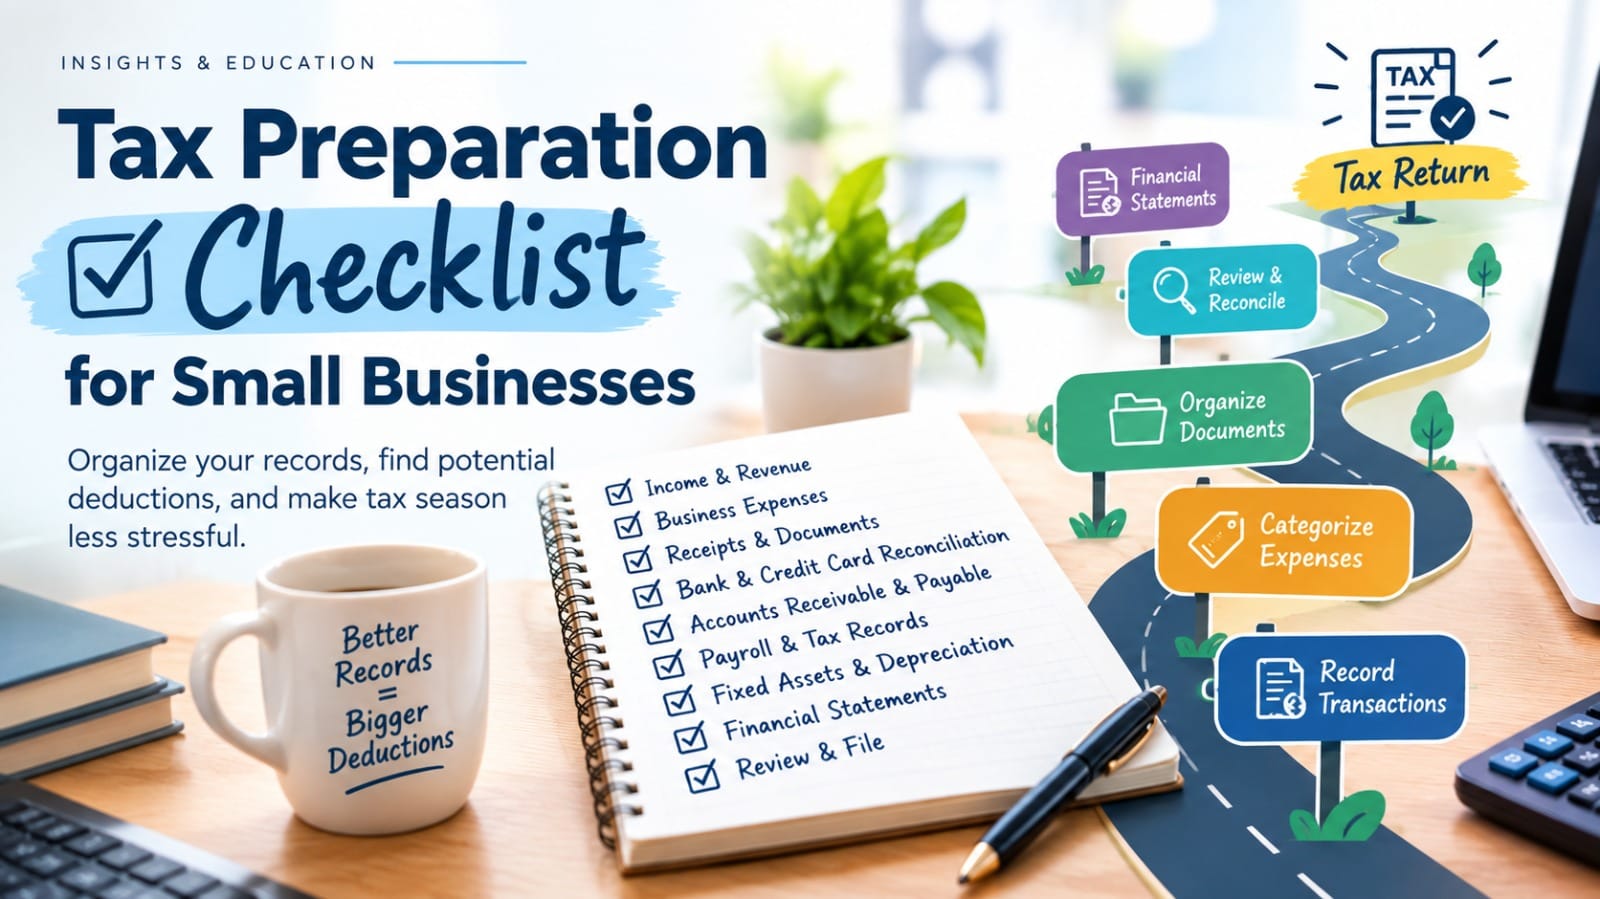
The Complete Tax Preparation Process
We can summarize the whole process as:
Collect Information
↓
Record Transactions
↓
Categorize Income & Expenses
↓
Reconcile Bank & Credit Cards
↓
Review AR & AP
↓
Review Payroll & Fixed Assets
↓
Separate Business & Personal Transactions
↓
Prepare Financial Statements
↓
Identify Missing Information
↓
Review Applicable Tax Rules
↓
Prepare Tax Return
↓
Review & File
Why Good Bookkeeping Makes Tax Preparation Easier
Tax preparation should not be viewed as a separate activity that begins only when tax season arrives.
It is connected to everything that happens during the year.
A simple transaction can eventually become part of the tax return.
For example:
Business Purchase
→ Transaction recorded
→ Correct category identified
→ Account reconciled
→ Supporting document maintained
→ Expense reviewed
→ Appropriate tax treatment determined
→ Included in tax preparation
This is why accurate bookkeeping and proper categorization are so important for tax preparation.
Good bookkeeping does not automatically determine whether an expense is deductible. The applicable tax rules determine the appropriate tax treatment. But well-organized books make it much easier for the tax preparer to identify, review, support, and properly report potentially deductible expenses.
Final Thought
Tax preparation does not begin when tax season starts. It begins with every transaction recorded throughout the year.
If transactions are recorded correctly, categorized properly, reconciled, supported with documentation, and reviewed regularly, the tax preparation process becomes more organized and efficient.